When this valuation is needed
Tax positions involving real property need a value that is documented, date-specific, and able to withstand review. These are the situations that call for a formal appraisal.
Capital Gain
Calculating a capital gain on the sale or disposition of property.

.png)
Change of Use
Establishing value at a change of use, for example a principal residence converted to a rental.
Transfer or Gift
Supporting an intergenerational transfer or gift of property.


Historical Value
Documenting value as of a specific historical date, such as the date a property was acquired or changed use.
What you receive

Established as of today's date
Compliant appraisal report


Comparable evidence and reasoning

Led personally,
by the principal.
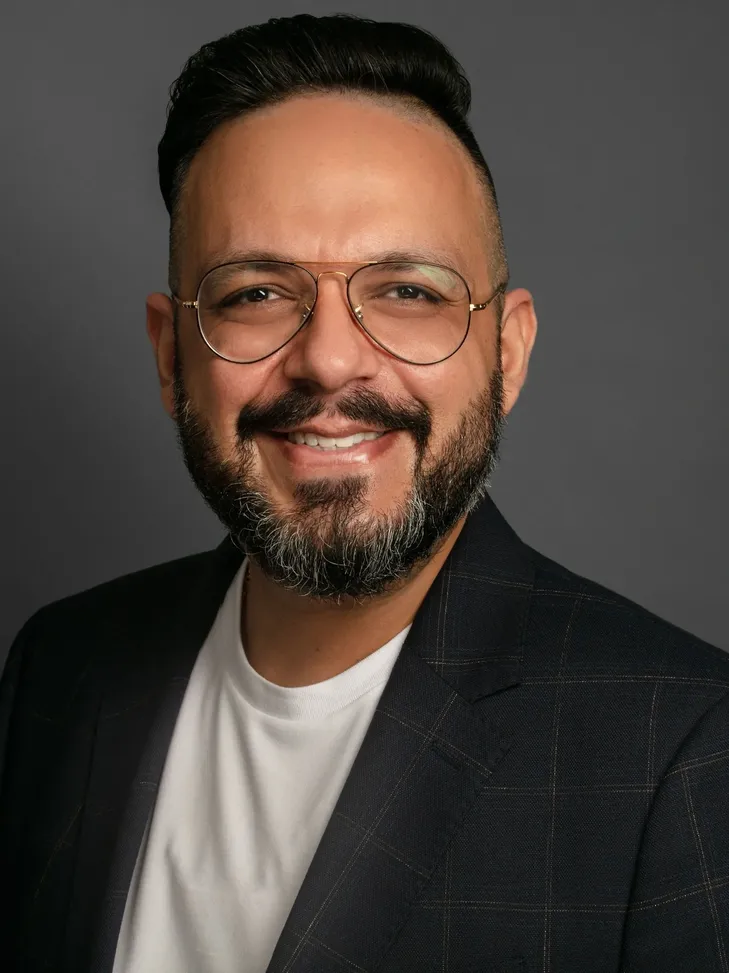
Appraise Wise is led by Sid Malhotra, MBA, P.App, CRA.
For more than twenty years he has valued the homes that resist easy valuation, and advised the owners, lawyers, accountants, and lenders who depend on getting it right. Every engagement is his, personally.
Trusted by the professionals who advise on value.
Family and estate lawyers, accountants, private lenders, and the region's leading luxury brokerages rely on Appraise Wise for valuations they can put their name beside.
Other Areas of Practice, One Standard of Rigor.
Sale & Pre-Listing

Divorce & Separation

Estate & Probate

Legal & Financing

Trusted by the Professionals
who advise on value.
Family and estate lawyers, accountants, private lenders, and the region's leading luxury brokerages rely on Appraise Wise for valuations they can put their name beside.
FAQs
Common questions about how a valuation is prepared, what the report contains, and how the process works. If yours isn't answered here, ask directly.
A capital gain is the difference between a property's value at acquisition (or at a deemed disposition) and its value at sale. Where either figure is not established by an arm's-length transaction, it has to be supported by an independent opinion of value. A documented appraisal gives your accountant a defensible basis for the number on the return.
Converting a property from one use to another — most commonly a principal residence becoming a rental, or the reverse — is treated as a deemed disposition for tax purposes. Value must be established as of the date the use changed, even though no sale occurred and no money changed hands.
Yes. A retrospective appraisal establishes value as of a specific historical date — the date a property was acquired, the date use changed, or another date the filing requires. The analysis reflects market conditions as they stood then, drawn from sales evidence contemporaneous with that date.
Where property is gifted or sold to a related party below market value, the CRA generally treats the transaction as occurring at fair market value regardless of the price paid. An independent appraisal establishes what that figure is, and documents how it was reached.
The report is prepared to CUSPAP standards, with the comparable evidence and reasoning set out in full and the effective date stated explicitly. It is written to be filed and, if questioned, to be defended.